
Quick answer
Ownright Custom Finance arranges home loans, private mortgages, bridging, caveat and business finance for Geelong borrowers, and works from Knoxfield, Victoria, within the same state. Geelong's mix of waterfront, growth corridors, the Bellarine and Surf Coast, rural land to the west and a changing industrial base creates deals that need a lender who reads them properly.
Key points
- Geelong, Bellarine Peninsula, Surf Coast and Golden Plains
- Victorian-based team, so local conditions are familiar
- Manufacturing, health, education and tourism incomes understood
- Holiday, lifestyle and rural-edge property considered
- Private mortgages and bridging for tight timing
- Suits
- Geelong and Bellarine owners, tradies, investors and growers with a tricky deal
- Security
- Homes, new estates, holiday properties, lifestyle blocks, commercial and industrial
- State bodies
- State Revenue Office Victoria and Land Use Victoria
- Australia-wide
- Yes
A city that reinvented itself
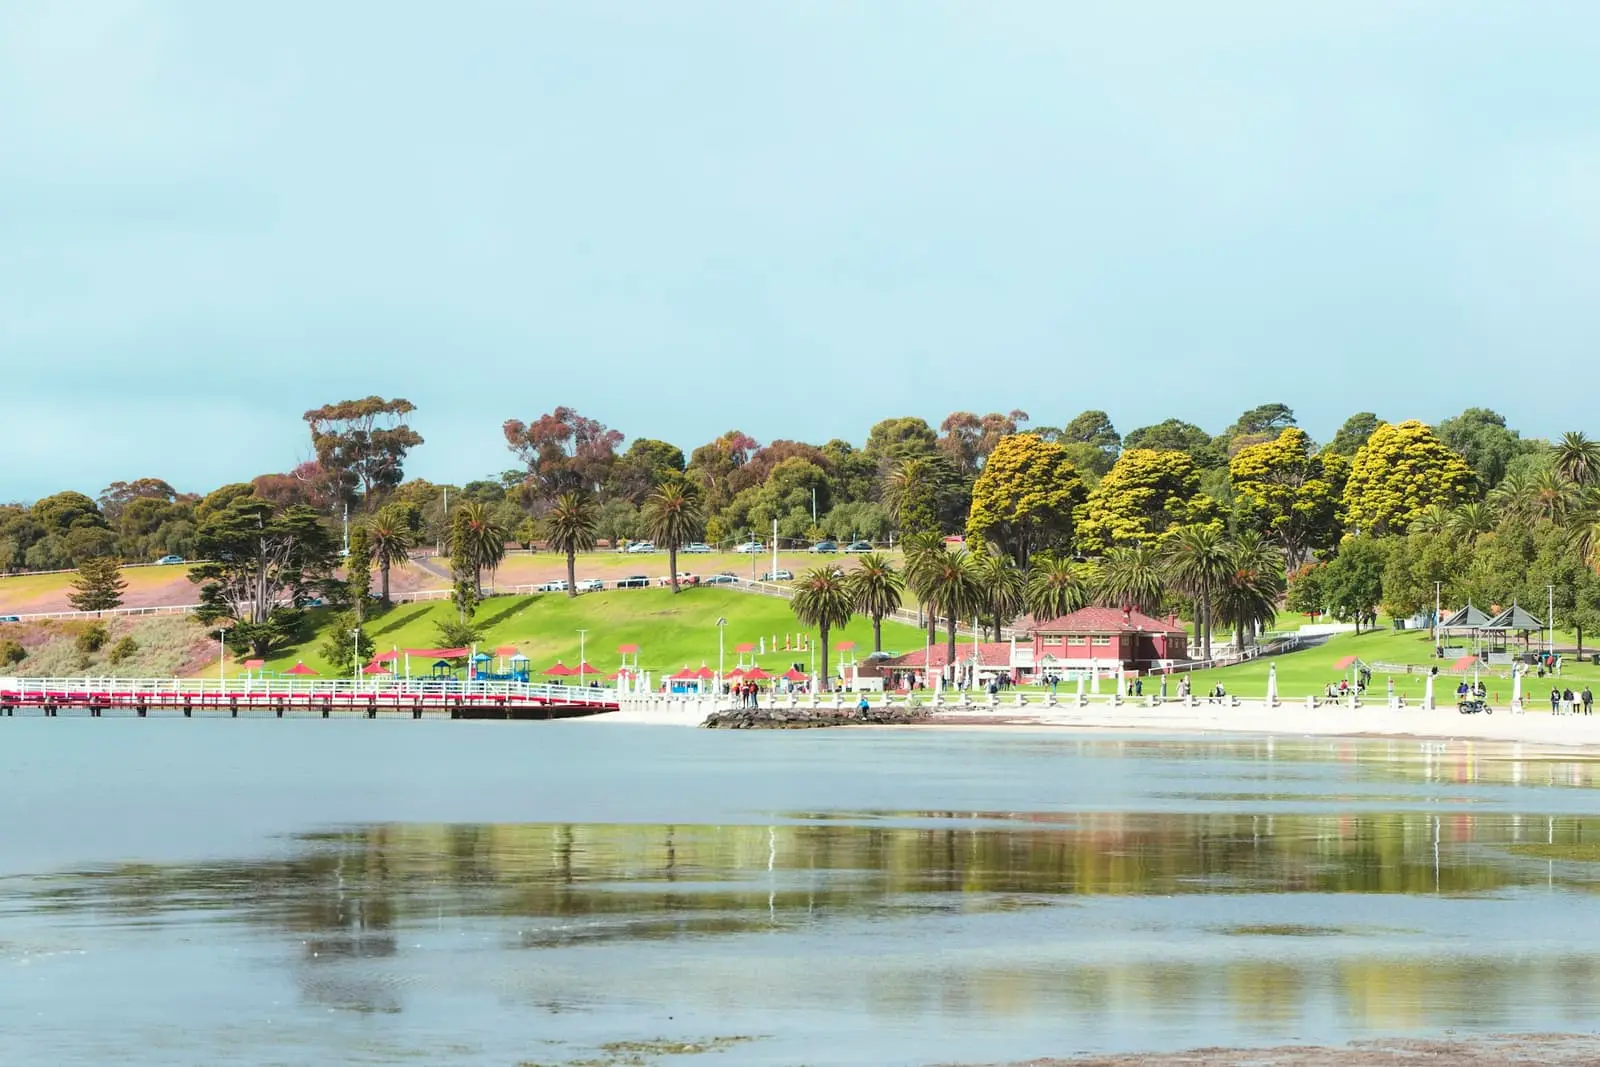
For much of the twentieth century Geelong made things: cars, wool products, fertiliser, aluminium. When car manufacturing wound down in the mid-2010s, the city turned towards health, education, advanced manufacturing, the NDIS workforce and a waterfront that now draws weekenders from Melbourne. Deakin University, Barwon Health and the port sit alongside new estates in Armstrong Creek and Lara, and holiday-home belts along the Bellarine Peninsula and the Surf Coast.
Ownright Custom Finance sits only a motorway drive away at Knoxfield, Victoria. Director Trevor Scott has more than 40 years in finance, and the team works with Victorian borrowers every day, so Geelong’s conditions are well-known territory.
What do Geelong borrowers tend to run into?
- Transition-era careers. People who moved from manufacturing into contracting, trades or their own business may have short trading histories.
- Growth-corridor purchases. New estates, house-and-land packages and delays in construction can strain settlement timing.
- Holiday and lifestyle property. Bellarine and Surf Coast homes mix investment, family use and short stays.
- Mixed family businesses. Personal and business finances tangled together, a common source of lender hesitation.
- Rural edges. Farmland towards Winchelsea, Inverleigh and the Golden Plains area.
Who is this page for?
Geelong homeowners and investors, tradies and small business owners, families building in the northern and southern growth areas, holiday-home owners on the Bellarine and Surf Coast, and rural landholders. If you have already tried a lender and been refused, that is a particularly good moment to ring us.
Related reading: Victoria lending overview and Melbourne loans.
The lender’s checklist, Geelong-style
| Lender question | In Geelong this often means |
|---|---|
| Can the property be valued reliably? | New-estate comparables, holiday homes, lifestyle blocks |
| Does income make sense? | Recent career change, sole trader or family company |
| Is the debt serviceable? | Existing commitments, tax liabilities, payment history |
| How will it end? | Sale, refinance or completion of works |
Non-bank lenders can be more flexible than major institutions on several of those points. Read more on our non-bank home loans page and the guide to refinance versus second mortgage.
How Ownright approaches a Geelong application
Our first job is to understand the whole story: what is being bought or refinanced, what the money is for and what has gone wrong so far. We then pick a lender group that fits instead of firing the application in every direction. A tradie with solid BAS and a blemish from two years ago needs a different door from a retiree wanting equity for a granny flat.
Where the clock is ticking, difficult loans from private lenders may allow a purchase to proceed or a debt to be cleared, with a refinance planned afterwards. Our experience is that preparation, not magic, makes the difference: complete documents, a clear explanation and an honest exit plan. Occasionally we find a solution that surprises people, which is where the line “if Ownright can’t find the solution, no one can” comes from.
Tell us about your Geelong property or project.
Illustrative Geelong scenarios
Illustrative only, with no real names.
The former factory worker turned contractor. After years as an employee, a borrower now invoices clients directly. The most recent lodged return shows only part of a year in business. A lender who accepts BAS and bank statements for a shorter period may fit.
The Bellarine holiday-home refinance. A couple’s lender will not renew an interest arrangement on a property that is used partly as a holiday let. A different lender, comfortable with holiday use, could take over.
The house-and-land delay. A new estate settles late and the buyer’s finance approval expires. Interim finance may cover the gap, then be replaced by a standard loan once the title issues. See lifestyle property loans if the purchase includes acreage.
How do Geelong’s neighbourhoods differ for lending?
Greater Geelong is large, and the lending picture changes with the suburb.
- Central Geelong and the waterfront. Apartments, converted warehouses and the Eastern Beach and Cunningham Pier precinct, popular with downsizers and weekenders.
- Newtown, Highton and Belmont. Established family suburbs with period homes and good schools, usually the easiest stock for mainstream lenders.
- Corio, Norlane and Lara. Closer to industry and the port, with different price points and a different borrower profile.
- Armstrong Creek and Charlemont. The south-eastern growth corridor with new estates, house-and-land packages and long construction timelines.
- Bellarine Peninsula. Ocean Grove, Queenscliff, Portarlington and Point Lonsdale, a mix of permanent residents and holiday homes.
- Surf Coast. Torquay, Anglesea and Lorne, where holiday letting and bushfire overlays shape lender attitudes.
- Golden Plains and the rural west. Winchelsea, Inverleigh and Bannockburn, with lifestyle acreage and grazing country.
Geelong’s employers have shifted as well. Ford and Alcoa wound down their local operations in the mid-2010s, while the National Disability Insurance Agency, WorkSafe Victoria and the Transport Accident Commission have established major offices in the city. Education, health, defence-related manufacturing and construction all employ large numbers of borrowers whose income histories do not look like those of a single-employer career.
How do short-stay rules affect a Bellarine or Surf Coast property?
Victoria’s State Revenue Office administers a short stay levy on certain short-stay accommodation, and councils may have their own planning rules. For a lender, the real question is simpler: how much of the property’s income comes from short stays, and is that use lawful and documented? A borrower with a booking history, a council permit position that is clear and a sensible split between personal and letting use presents far better than one with a handful of platform screenshots.
Some lenders treat a part-time holiday let as ordinary investment income; others cap how much they will count or decline the security altogether. Choosing the right lender before applying keeps the file out of the declined pile.
What can a growth-corridor buyer do about delays?
New estates in Armstrong Creek, Lara and surrounding areas can move slower than the contract timetable suggests. Titles may be late, builders may be backed up and an approval that was valid in January may expire before the keys change hands. A buyer in that position has a few options:
- Ask the lender about extending or reissuing the approval before it lapses
- Check whether the contract allows for a delayed settlement and what penalties apply
- Consider interim finance if the land has settled but the build is not complete
Early warning is the common thread. Telling your broker as soon as a delay appears gives more room to find a path than waiting for the final week.
Mistakes to avoid
- Letting a finance approval lapse during construction delays.
- Mixing personal and business expenses in ways that confuse assessors.
- Assuming a holiday home will be treated like a family home.
- Applying for multiple loans in quick succession.
- Going short-term without a written exit.
Documents worth gathering
Identification, recent loan statements, rates notices, the contract of sale or building contract, bank statements, tax returns and BAS for business owners, and any details of holiday-let income.
Victorian authorities
The State Revenue Office Victoria administers duty, concessions and land tax, and Land Use Victoria handles titles. We coordinate with your conveyancer so lender conditions and statutory steps line up smoothly.
Which Geelong situations suit which structure?
| Situation | Direction often explored | Related page |
|---|---|---|
| Career changer now invoicing clients | Short-history self-employed assessment | Self-employed home loans |
| Holiday-home owner whose lender is withdrawing | Refinance with a lender that accepts holiday use | Home loan refinance |
| Buyer caught by a settlement delay | Interim or bridging finance | Interim finance |
| Family business with mixed personal and business debt | Restructure and consolidate | Debt consolidation loans |
| Lifestyle acreage near Inverleigh | Lender that understands lifestyle land | Lifestyle property loans |
Why does Trevor Scott’s experience matter for a Victorian regional city?
Geelong sits between metropolitan and regional lending, and the files that arrive from it often blend both. A tradie might live in Highton, work across Melbourne’s west and own a block at Torquay. A retiring farmer might want to buy a townhouse in the city and hold onto the paddock. Forty-plus years in finance gives Trevor Scott and the team a long memory of how lenders treat those hybrids, and which ones ask the right questions rather than rejecting on a postcode.
Because our head office is in Knoxfield, we are close enough to meet in person when that helps and set up to handle the entire process digitally when it does not. To talk through your Geelong deal, use our application page and tell us the key facts.
Next step
Geelong is close enough to Melbourne to feel familiar and different enough to need a considered approach. Contact Ownright about your Geelong finance and we will tell you plainly where the best prospects lie.
How it works, step by step
- 1
Step 1
Tell us the property, the challenge and the date you are working to.
- 2
Step 2
We choose a lender type to suit, from non-bank to private.
- 3
Step 3
A single, organised submission goes in with context on income or title issues.
- 4
Step 4
We manage the lender and your conveyancer through to settlement.
Frequently asked questions
Is Ownright local to Geelong?
Our head office is at Knoxfield in Melbourne's outer east, so we work within the same state and know Victorian conditions well. Geelong is roughly an hour from Melbourne, and we handle applications by phone, email and secure upload. We can also arrange for local valuers to inspect your property.
Can I get a loan on a Bellarine or Surf Coast holiday home?
Often, yes. Holiday homes in places like Ocean Grove, Torquay or Barwon Heads can be financed, though lenders differ on short-stay use and investment treatment. We ask how the property is used and approach lenders whose policy matches, including private options where timing is tight.
My income comes from a family business in Geelong. Will that help or hinder?
Either, depending on how the books look. Lenders want to see consistent earnings, tax compliance and the borrower's role. Family businesses sometimes have mixed personal and business spending, which complicates assessment. We help organise the picture and find lenders comfortable with it.
What if I need money quickly for a Geelong purchase or tax bill?
Bridging, caveat or private mortgage finance can sometimes be arranged quickly where there is equity and an exit. Speed depends on the lender, the security and document readiness, so no timeline is guaranteed. We tell you early whether your deadline looks workable.
Do you lend on rural land near Geelong, such as Golden Plains or Colac?
Yes. Ownright arranges rural property and farm lending across Victoria and beyond, including grazing, cropping and lifestyle blocks west and north of Geelong. Land size, water, zoning and income all influence lender choice. We match the property and your plan to a suitable lender.
Can a second mortgage help if my bank will not extend my loan?
Sometimes. A second mortgage can release equity without refinancing the first loan, useful when the existing loan has good features or when refinancing is hard. Eligibility depends on equity, purpose and exit. We explain the realistic terms before you proceed.