
Quick answer
Ownright Custom Finance arranges home, private mortgage, bridging, caveat and business loans for Hobart borrowers, lending Australia-wide from Knoxfield, Victoria. Hobart's small, tightly held market, tourism-driven income, short-stay properties and nearby orchards and farms create situations bigger lenders can misread. We find lenders who understand Tasmanian security and the people behind it.
Key points
- Hobart, the Derwent Valley, Huon Valley and Tasman Peninsula
- Tourism, hospitality and seasonal income explained to lenders
- Short-stay and heritage properties considered
- Orchard and farm-edge security understood
- Arranged by phone, with local valuers and solicitors
- Suits
- Hobart owners, operators and buyers with seasonal income or atypical property
- Security
- Homes, heritage buildings, short-stay properties, orchards and commercial premises
- State bodies
- SRO Tasmania and Land Titles Office
- Australia-wide
- Yes
Why does Hobart need a different conversation?
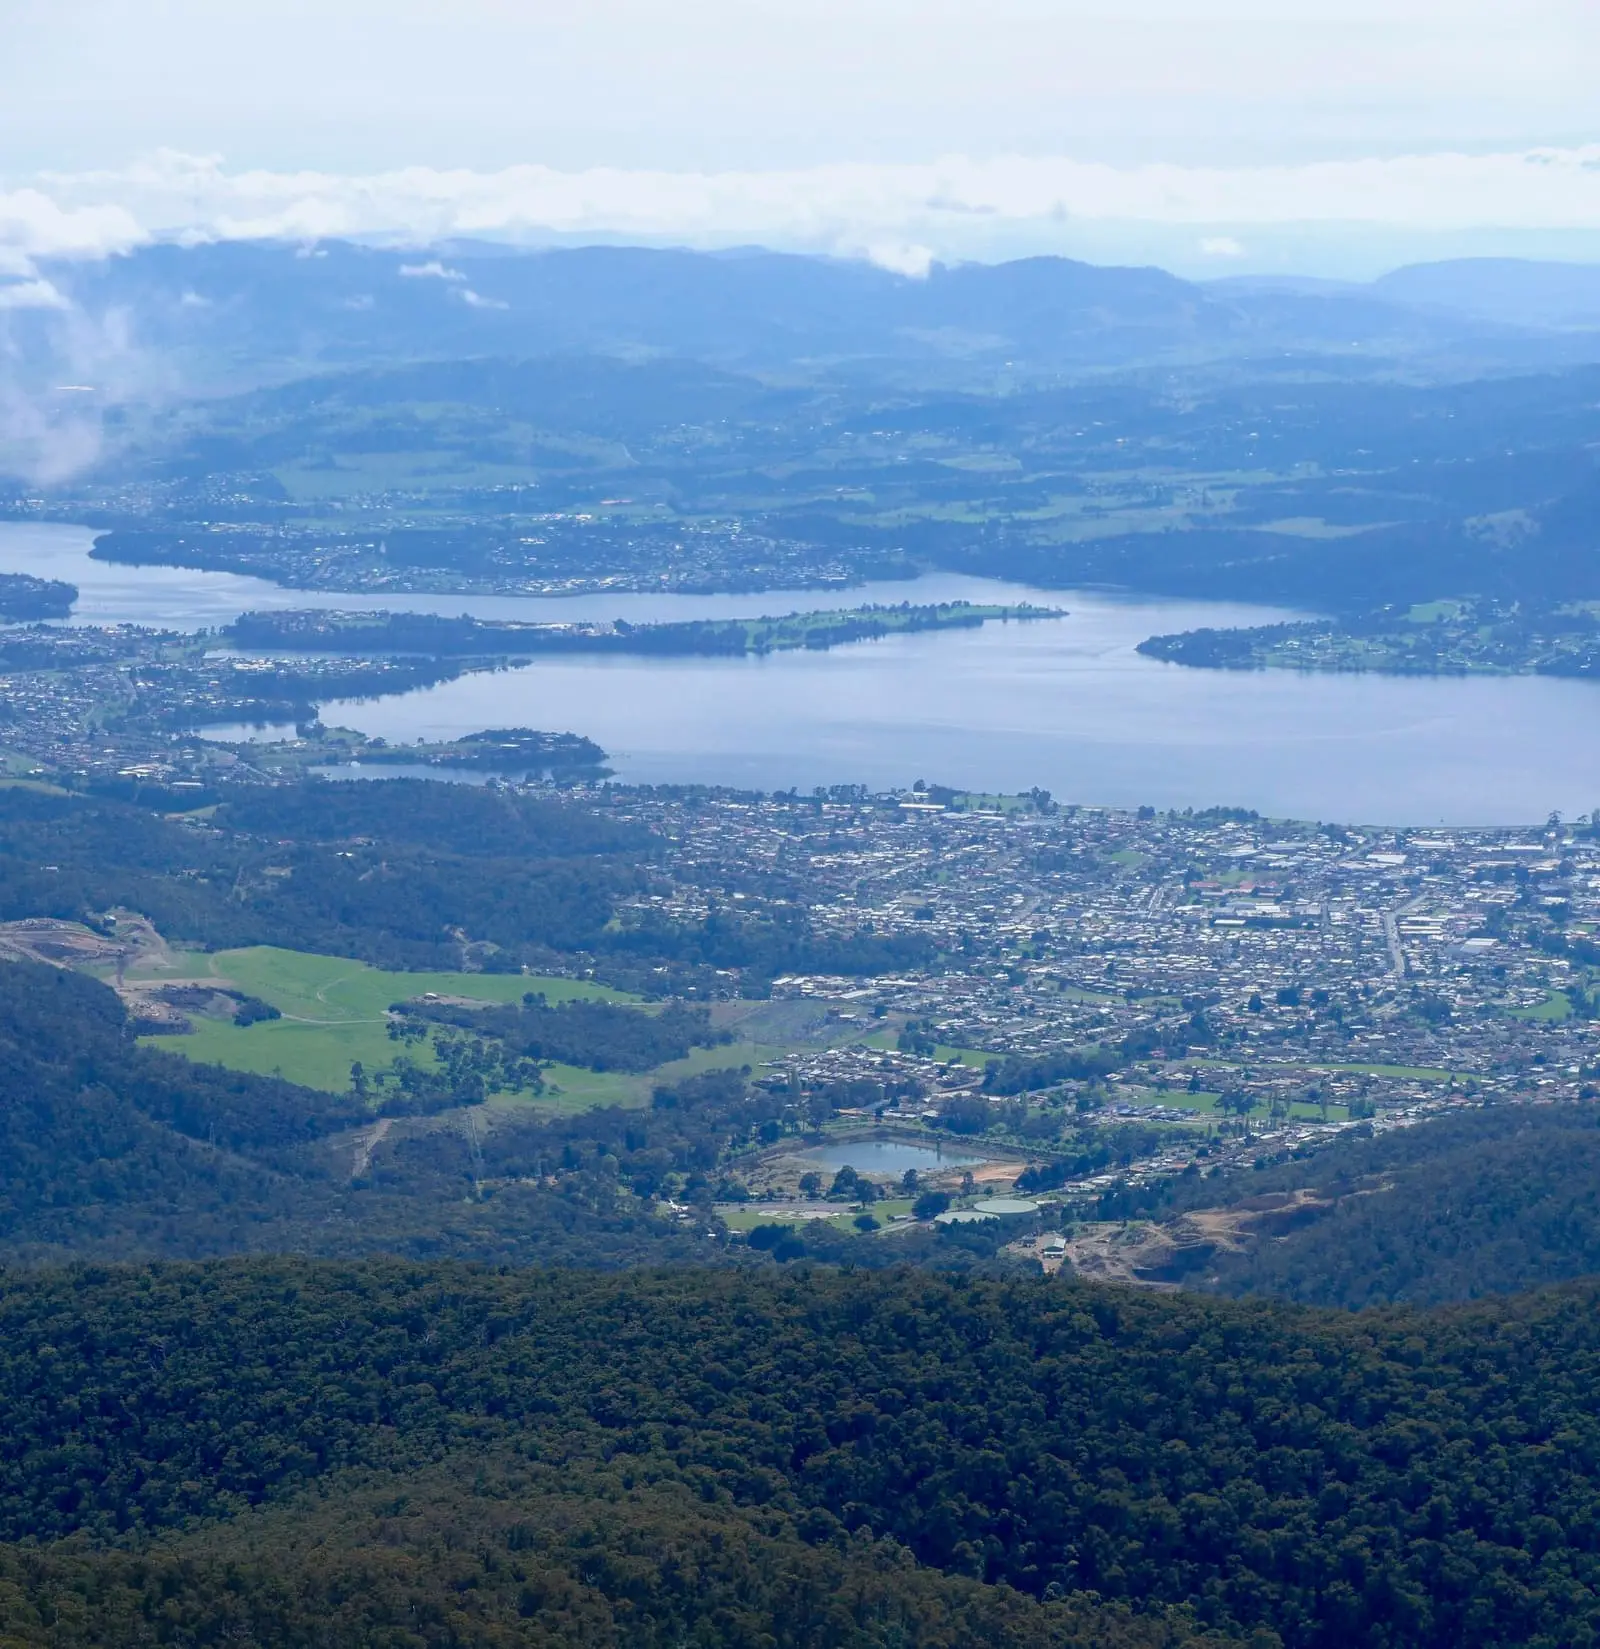
Hobart is Australia’s second-oldest capital, wedged between the Derwent estuary and kunanyi / Mount Wellington. Its streets are narrow, its homes are often old and its property market is small enough that one sale can change the picture for a whole suburb. Over the past decade, tourism, arts, hospitality and remote-working newcomers have added new layers, while the Huon and Derwent valleys keep orchards and farms close at hand.
Ownright Custom Finance is based in Knoxfield, Victoria, across Bass Strait, and director Trevor Scott leads a team arranging finance in every state and territory. Hobart is just one more place where a considered, experienced approach pays off.
The kinds of cases that suit us
- Heritage and character homes. Sandstone cottages, Georgian terraces and weatherboards with covenants can confuse valuation models.
- Short-stay accommodation. Holiday rentals and B&Bs sit between residential and commercial lending.
- Tourism and hospitality operators. Cafés, tour operators and accommodation providers with strong summers and thin winters.
- Orchard, vineyard and farm-adjacent land. Cherries, apples, berries, hops and wine grapes are all part of the regional economy.
- People relocating. Mainland buyers moving to Hobart often have income and assets spread across places.
Who benefits most?
Hobart homeowners and investors, small business owners with seasonal cash flow, rural landholders in southern Tasmania and interstate buyers eyeing island property.
If you want a state overview, read our Tasmania lending page.
What do lenders weigh?
| Area | Hobart-specific angle |
|---|---|
| Security | Heritage status, slope and access, bushfire or flood overlays, short-stay approvals |
| Income | Seasonal averages, sole trader returns, multiple income streams |
| Equity | Often the deciding factor for private and second-mortgage options |
| Purpose and timing | Purchases, renovations, tax debts, estate settlements |
Seasonal income deserves special attention. A lender who looks at a quiet July in isolation may misjudge a business that earns most of its profit from December to March. We help present a full-cycle picture, and our seasonal business loans page discusses the typical approaches.
How Ownright works a Hobart file
We start by asking what the property really is and how the money will be repaid. A short-stay townhouse with a manager, a hops grower with an expansion plan and a café owner with a tax bill each need a different lender profile. Then we shape the submission to match.
Some Hobart borrowers need breathing space more than permanent change. Interim finance can hold a position while a sale completes or a longer-term lender finishes assessment. Our guide to bridging loan exit strategies explains why an exit plan matters.
Tell us what is happening with your Hobart property and we will explain where the doors might be.
Illustrative Hobart scenarios
Illustrative only.
The heritage cottage buyer. A buyer wants a listed cottage requiring work, and the preferred lender will not fund until repairs are complete. A private first mortgage may carry the purchase and works, then be refinanced once the home is finished.
The tour operator with a quiet season. Income is clear across a year but patchy by month. A lender who reads full-year bank statements may suit better than one fixated on recent months. See hospitality business loans.
The orchardist with a good crop and a hard bank. Harvest costs arrive before the packing-shed payment. Short-term secured finance against farm or home property may cover labour and freight. More detail on orchard finance.
What does the Hobart region look like to a lender?
Southern Tasmania packs several property types into a short drive.
- Inner Hobart. Battery Point, Sandy Bay, North Hobart and West Hobart, with heritage cottages, converted warehouses and steep blocks with water views.
- The Eastern Shore. Bellerive, Lindisfarne and Rokeby, a popular alternative to the western shore with a mix of older homes and newer estates.
- Glenorchy and the northern suburbs. Larger blocks, industrial areas and a strong small-business presence.
- Kingborough and Kingston. A growing southern corridor, home to Australian Antarctic Division headquarters and a pool of government and science jobs.
- The Derwent Valley. New Norfolk and surrounds, long associated with hop growing.
- The Huon Valley. Apples, cherries, berries and aquaculture inland and along the channel.
- Coal River Valley and the east coast. Cool-climate vineyards at Richmond, Tasman Peninsula tourism and Bruny Island holiday homes.
ABS figures put Greater Hobart at about 255,000 people at June 2025, with growth of just 0.2 per cent in 2024-25, the slowest of the capital cities. A small, slow-moving market means fewer comparable sales, which is one reason valuers and lenders can disagree about unusual properties.
How are Tasmanian titles and duty handled?
Land titles in Tasmania are administered through the Land Titles Office, which sits within the Department of Natural Resources and Environment Tasmania and is run by the Recorder of Titles. Duty and related concessions are administered by SRO Tasmania. For most loans these are background steps for your conveyancer, but they matter when timing is tight: a title issue, an old easement or a missing plan can stall settlement just as a bridging lender is counting days.
For heritage properties, ask early whether a heritage listing or planning overlay applies. Overlays do not stop finance, but they can affect what renovations are possible, which in turn affects how a lender values a “renovate later” plan.
What about bushfire, flood and access?
Parts of the Hobart hills, the Tasman Peninsula and the Huon and Derwent valleys sit in bushfire-prone areas, and some lower-lying spots near rivers and the waterfront have flood history. Lenders and insurers often want to know the answer before they commit. Narrow roads, shared driveways and steep gradients can also affect access for valuers, builders and emergency vehicles.
None of this makes a property unfinanceable. It does mean the borrower who has an insurance quote, a clear access description and any overlay information in the file is usually in a better position than one who hopes nobody asks.
Mistakes to avoid
- Presenting only the strongest or weakest season rather than a full year.
- Ignoring planning approvals for short-stay use.
- Underestimating how restoration costs will be treated.
- Applying for several loans in a rush after one decline.
- Not keeping an accountant in the loop for business income.
Documents to prepare
Identification, existing loan statements, rates and land tax notices, the contract of sale or title, a full year of bank statements, tax returns and BAS where relevant, and for short-stay properties, booking history and approvals.
Tasmanian authorities
SRO Tasmania handles duties and concessions, and titles are registered through Tasmania’s Land Titles Office. We coordinate with your solicitor so lender steps and statutory steps line up.
How should a mainland buyer prepare for a Tasmanian purchase?
Interstate buyers often underestimate how different a small island market feels. Comparable sales may be few, auction results can swing a suburb, and the right surveyor, builder or conveyancer may be booked weeks ahead. Lining up the finance first matters even more here. A buyer who has a lender comfortable with the property type, a clear picture of any rental or holiday-let income and a plan for the existing home on the mainland can move when the right place appears, instead of scrambling after the offer.
How do Hobart scenarios map to finance structures?
| Situation | Direction worth exploring | Related page |
|---|---|---|
| Mainlander relocating with income in two states | Lender comfortable with interstate and mixed income | Non-bank home loans |
| Short-stay owner facing a lender policy change | Refinance to a lender that accepts holiday letting | Investment property loans |
| Seasonal operator needing a winter buffer | Line of credit or short-term facility | Seasonal business loans |
| Heritage buyer needing a staged renovation | Private first mortgage then refinance | Private first mortgages |
| Orchardist with harvest costs ahead of income | Short-term secured finance | Horticulture and orchard loans |
How does Trevor Scott’s experience help in a small market?
In a market where everyone knows someone, discretion and judgement matter. Trevor Scott has spent more than 40 years in finance and leads a team that has seen property cycles come and go. That experience helps with the practical side of Tasmanian deals: knowing which lenders will look at a one-off property without reaching for a template, and which borrowers are better served by a calm, staged plan than a rushed application.
Being based in Knoxfield, Victoria, also means we are used to working across Bass Strait by phone and email. Documents are digital, titles are handled by your conveyancer, and valuations are arranged locally. If you want a frank assessment before you commit to a purchase or a restructure, reach out to Ownright and tell us about your Hobart property.
Where to from here?
Tasmania rewards people who know it, and the lending side is no exception. If a lender has not understood your Hobart property or your income, get in touch with Ownright and let us look for the better fit.
How it works, step by step
- 1
Step 1
A short conversation about the property, the purpose and the pressure point.
- 2
Step 2
We choose between mainstream, non-bank and private pathways based on the story.
- 3
Step 3
Documents are bundled with a clear explanation of any seasonality or unusual features.
- 4
Step 4
We shepherd the file through valuation, approval and settlement.
Frequently asked questions
Can I borrow against a Hobart short-stay property?
Sometimes. Lenders differ on how they treat short-stay rental income and zoning. Some are comfortable if bookings are documented and the property is properly approved; others treat it as higher risk. We find out which camp suits your property and prepare income evidence to match.
My income from tourism is seasonal. Will that stop me getting a loan?
It does not have to. Lenders assess seasonal income by averaging periods or looking at bank statements across a full cycle. A lender who understands tourism and hospitality will treat it more fairly than one using a rigid template. We help present the full year, not just the quiet months.
Do you help with heritage-listed homes in Battery Point or Sandy Bay?
Yes, we can approach lenders comfortable with heritage and character homes. Restrictions on renovation, age of construction and insurance can affect valuations, so we gather the facts early. Where a mainstream lender is cautious, private options may suit while a longer-term plan is arranged.
Can Ownright help with Huon Valley or Derwent Valley orchards?
Yes. Orchard and rural lending in Tasmania covers fruit, hops, wine and mixed farms, and each has its own cash-flow rhythm. We look at lenders who know horticulture and consider private or short-term options when seasonal timing is tight. Our orchard loans page explains the basics.
How fast can a Hobart bridging loan be arranged?
Occasionally quickly, but it depends on the lender, the security and how swiftly documents arrive. We cannot promise a timeline. What we can do is tell you early whether your date is realistic, and what an alternative plan would look like if it is not.
I live interstate and own property in Tasmania. Is that a problem?
No. Many Tasmanian properties are owned by interstate residents. We arrange finance for security in Hobart and beyond, working remotely and coordinating with local valuers and conveyancers. Tell us where you live, where the property is and what the loan needs to achieve.