
Quick answer
Ownright Custom Finance arranges home loans, private mortgages, bridging, caveat, development and business finance on the Gold Coast, lending Australia-wide from Knoxfield, Victoria. The Gold Coast's high-rise apartments, canal homes, short-stay investments, hinterland acreage and construction industry produce complicated deals that standard lenders often decline. We find lenders suited to each.
Key points
- Surfers Paradise to Coolangatta, plus the hinterland
- Apartments, canal homes, short-stay and development sites
- Builders, tradies and hospitality owners with lumpy income
- Bridging and private lending for fast-moving purchases
- Interstate and overseas-income buyers considered
- Suits
- Coast investors, builders, retirees and operators with atypical security or income
- Security
- High-rise and low-rise units, canal and beachfront homes, hinterland acreage, commercial
- State bodies
- Queensland Revenue Office and Titles Queensland
- Australia-wide
- Yes
Why is the Gold Coast its own lending world?
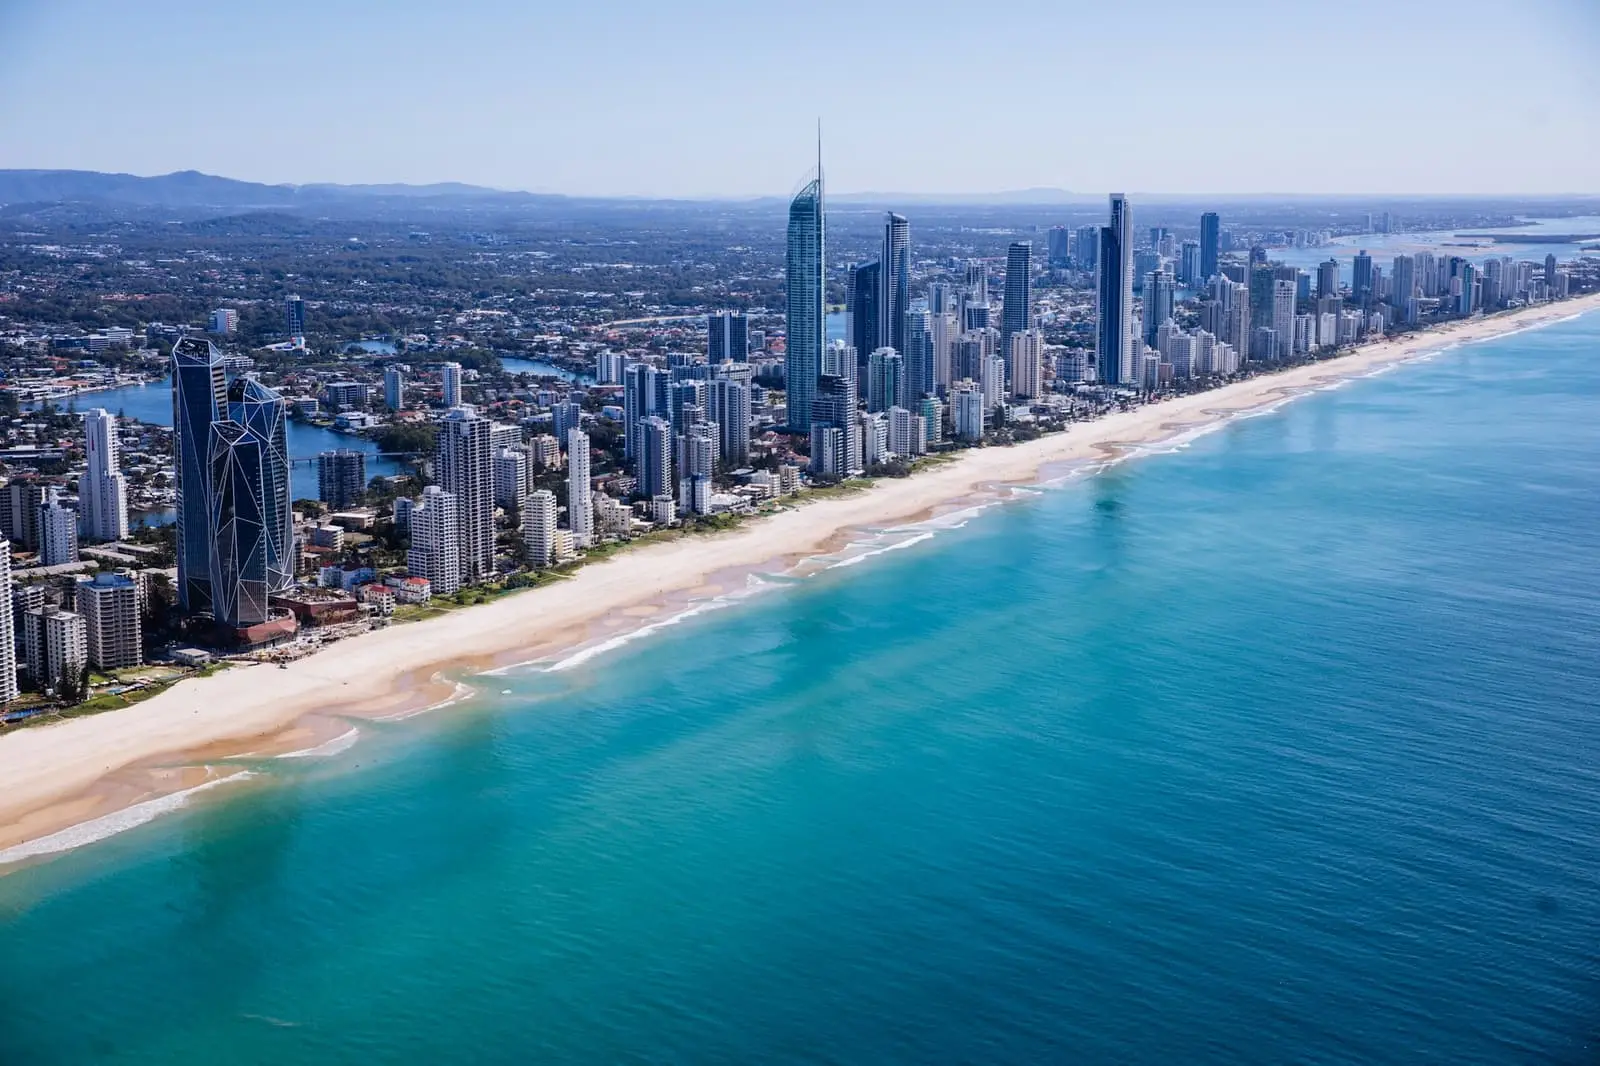
The Gold Coast is a 50-odd kilometre ribbon of beach, canals and towers, backed by a green hinterland of rainforest and acreage. It hosted the 2018 Commonwealth Games, draws interstate and international buyers, and has one of the country’s busiest construction sectors. Tourism, hospitality, building and property services drive much of the economy.
That blend creates unusual borrowers: retirees with strong assets, developers with a site and a plan, hospitality owners with seasonal swings, investors holding short-stay apartments, and builders carrying a lot of work in progress. Mainstream credit policy often struggles to read them.
Ownright Custom Finance arranges loans in every state and territory from its head office in Knoxfield, Victoria. Director Trevor Scott has more than 40 years in finance, and the Gold Coast is a market where creative, well-structured solutions are regularly needed.
What kinds of Gold Coast cases come up?
- Apartment restrictions. Small units, large complexes and off-the-plan purchases attract policy limits.
- Short-stay income. Holiday letting can be profitable but is treated cautiously.
- Canal and beachfront homes. High value, specific insurance issues and sometimes ageing seawalls.
- Development sites. Small-scale developers need staged or short-term funds before sales.
- Building and trades businesses. Strong turnover, tight cash, and tax obligations that can pile up.
- Hinterland lifestyle land. Larger blocks above the coast with their own rules.
Who benefits from this page?
Coast residents and investors, interstate buyers, builders and developers, hospitality operators and landowners who want to know their options when the first lender says no. For the wider state picture, read Queensland loans; for the capital, see Brisbane loans.
How lenders look at a Gold Coast application
| Question | Gold Coast flavour |
|---|---|
| Is the property mainstream? | Building size, unit size, short-stay use, cladding or body corporate issues |
| Is the income verifiable? | Rental history, business turnover, super or foreign income |
| Is there equity? | Particularly important for private loans in a fast-moving market |
| Is the exit defined? | Sale, refinance, project completion |
Where mainstream lenders see a problem, private lenders may see a manageable risk if equity and exit are sound. Our investment property loans page and development finance page go deeper into the investor and developer side.
How Ownright approaches Gold Coast deals
We start with the building, the block or the business. A twelfth-floor Broadbeach unit needs a different lender from a Mudgeeraba acreage, and a development site needs another again. We prepare a submission that answers the likely lender questions up front: body corporate details, insurance, income evidence and a believable exit.
Because the market can move quickly, bridging finance is a regular topic. It can sometimes hold a purchase in place while a sale completes or a longer-term lender finishes assessment. Speed depends on the lender, the security and the documents, and we never promise a date.
Tell us the Gold Coast details and we will say where the options lie.
Illustrative Gold Coast situations
Illustrative only.
The holiday-unit investor. An investor wants to refinance a short-stay apartment, and the current lender is withdrawing. Lenders who accept documented holiday letting may fit, as discussed above.
The small developer. A builder has a site approved for a handful of townhouses and needs funds ahead of presales. Staged or short-term development finance may help. See the guide for first-time developers.
The canal-home owner with a tax bill. Plenty of equity, an ATO arrangement falling apart. A second mortgage may clear the debt and restore breathing room.
How do the different parts of the Gold Coast behave?
Lenders sometimes treat the whole coast as one postcode block, but the strip changes character every few kilometres.
- Surfers Paradise and Broadbeach. Dense high-rise, many apartments with short-stay use and large bodies corporate.
- Southport and Parklands. The city’s civic and health centre, with the Gold Coast University Hospital and a Griffith University campus supporting professional and student housing demand.
- Burleigh, Palm Beach and Currumbin. Beachside suburbs with a mix of older cottages, knockdown-rebuilds and townhouses.
- Coolangatta and Tweed border. A twin-state economy, which creates cross-border purchases, rentals and jobs.
- Helensvale, Coomera and Pimpama. Growth corridors to the north with new estates, house-and-land packages and a steady stream of first-time builders.
- The hinterland. Mudgeeraba, Tamborine Mountain, Numinbah Valley and Springbrook, where steep acreage, water supply and road access shape what a lender will accept.
Matching the right lender to the right strip is half the work. A twelfth-floor unit and a three-hectare Tamborine block should never be in the same submission template.
What do foreign and interstate buyers need to know?
Queensland applies additional foreign acquirer duty to certain residential land purchases by foreign persons, on top of normal transfer duty. The Queensland Revenue Office explains that it applies to land used solely or primarily for residential purposes, including homes, apartments and vacant land intended for a home. That affects the cash a foreign buyer needs on settlement day, and therefore the loan size, so it is worth raising with your conveyancer before an offer is made.
Interstate buyers face fewer special rules, but they often arrive with income, deposits and assets scattered across states. We help organise that into one coherent picture so a lender can follow it.
What does a body corporate file need to show?
For apartments and townhouses, lenders often look past the unit and into the building. Documents that commonly matter include:
- The most recent body corporate financial statements and sinking fund position
- Notices of special levies or major works
- Insurance certificates for the building
- Any short-stay or letting-pool arrangements and the rules around them
- Building age, construction type and unit size
A well-run complex with healthy reserves is easier to place. A building facing large repair bills can make a lender cautious, even when the unit itself looks fine. Reading these papers before you sign saves surprises later.
Mistakes to avoid on the coast
- Buying a small apartment without checking lender appetite first.
- Overstating short-stay income without documentation.
- Underestimating body corporate costs and special levies.
- Taking short-term money without an exit.
- Ignoring insurance requirements for canal and beachfront homes.
Documents that help
Identification, existing loan statements, rates notices, body corporate details, short-stay booking history, tax returns and BAS, bank statements, development approvals and quotes where applicable.
State authorities
The Queensland Revenue Office oversees duty and concessions, including those affecting foreign buyers, and Titles Queensland manages registrations. We coordinate with your conveyancer so each step lines up.
What does a strong Gold Coast submission contain?
A good file reads like a short briefing. It states what the property is, who owns it and how the loan will be repaid, then backs each point with a document. For a coast deal that usually means a one-paragraph summary of the plan, the title details, a clear income picture covering both regular earnings and any holiday letting, building and insurance information, and a written exit if the money is short-term.
Assessors on the coast see a lot of files that look similar on the surface: another apartment, another builder, another refinance. The submission that explains why this one is sound, in plain English and with the paperwork attached, tends to move faster than one that leaves the reader to work it out.
Which Gold Coast scenarios suit which structure?
| Scenario | Path often considered | Related page |
|---|---|---|
| Auction win with settlement looming | Bridging against existing equity | Bridging finance |
| Investor refinancing a holiday apartment | Lender that accepts documented short-stay income | Investment property loans |
| Builder with delayed progress payments | Secured short-term facility | Short-term mortgages |
| Retiree with equity and modest income | Asset-based assessment | Private mortgages |
| Small developer awaiting presales | Staged development funding | Development finance |
Why does Ownright suit a market that moves quickly?
Speed on the coast usually comes from preparation rather than shortcuts. The borrowers who settle smoothly tend to be the ones who knew early which lender suited the security, had the body corporate papers in hand and had a written exit for any short-term money. Trevor Scott’s four decades in finance help us spot the sticking points before they cost a contract.
We cannot promise a date, because timing depends on the lender, the security and how quickly documents arrive. What we can do is say, early and honestly, whether your timetable looks achievable and what would make it more likely. If you are weighing an offer, an auction or a refinance on the Gold Coast, send us the details and we will map the realistic options.
What now?
The Gold Coast rewards speed and structure. If you have a property or project that does not fit a standard box, start the conversation with Ownright and we will work through the realistic paths with you.
How it works, step by step
- 1
Step 1
Describe the property, the plan and the deadline.
- 2
Step 2
We match the security type, such as apartment, canal home or land, with a lender who accepts it.
- 3
Step 3
A tidy submission covers body corporate, income and exit details.
- 4
Step 4
We coordinate valuation, approval and settlement with your solicitor.
Frequently asked questions
Do lenders restrict apartments on the Gold Coast?
Some do. Policies can limit small apartments, high-density buildings, off-the-plan units or those with heavy short-stay use. Others lend comfortably. We check the building and unit size early and approach lenders whose policies fit, with private options where a bank-style lender will not proceed.
Can I borrow against a short-stay holiday apartment?
Often, though lenders vary in how they treat holiday letting income and body corporate rules. Documented bookings and approvals help. We prepare the income picture and approach lenders who accept it, rather than discovering a policy clash after you have committed.
Is bridging finance useful for Gold Coast auctions and tight settlements?
It can be, where there is enough equity and a clear sale or refinance plan. The coast's market can move quickly. Timing depends on lender, security and documents, so we cannot promise a date, but we can say early whether yours looks realistic.
I am a builder on the Gold Coast with a cash-flow squeeze. What are my options?
Builders often have strong work in hand but delayed progress payments or tax obligations. Secured short-term finance against property, or a second mortgage, may help bridge the gap. Lenders look at equity, exit and the business. We outline options before you commit to anything.
Can you help with hinterland acreage in Tamborine, Currumbin Valley or Springbrook?
Yes. Hinterland acreage sits between residential and rural lending, and lenders treat steep land, access and dwelling size differently. We find lenders comfortable with lifestyle acreage and discuss options such as private lending if timing or income evidence is complicated.
Do you lend to buyers living overseas or on foreign income?
Some lenders consider foreign income or non-resident borrowers, with extra conditions. Eligibility depends on residency status, foreign investment rules and the lender. We discuss your circumstances and explain what may be possible before you invest time in an application.